The financial close process combines transactions, reconciliations, adjustments and reviews to ensure that the financial statements are accurate. Without good control of close activities, there may be a delay in reporting, or errors may go undetected. Financial close controls support accountability, accurate record-keeping and timely financial reporting. It is also crucial to understand the applicability of internal financial control to consider whether the internal controls in place are sufficient to address financial reporting risks.
Why Financial Close Controls Are Important
A financial close comprises several teams and interdependent activities. If a delay occurs in one part, it will impact on the whole reporting cycle. For instance, if business units are not submitting their books on time or not reconciling them effectively, finance teams may not be able to complete the reconciliation process on time.
Effective controls can assist organizations to:
- Minimize duplication and mistakes
- Identify unusual transactions in a timely manner.
- Check or reconcile account balances appropriately
- Maintain supporting documentation
- Have clear review and approval processes in place
- Support consistency in financial reporting.
As organizations grow across locations, business units or accounting systems, these controls become increasingly important.
Key Controls Within the Close Process
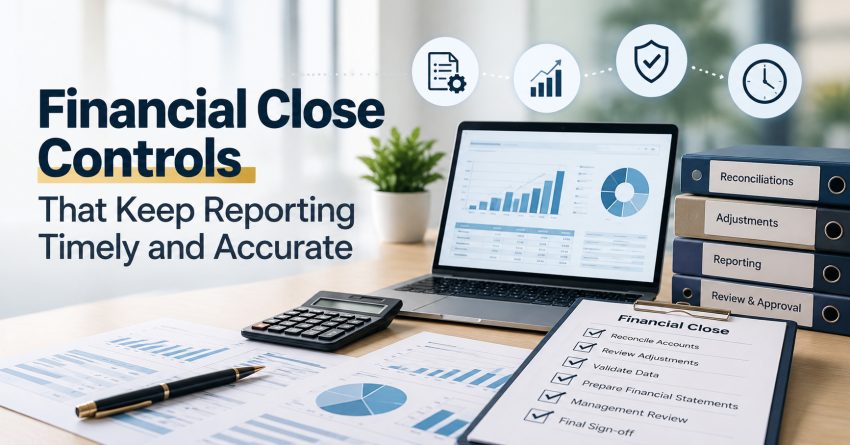
A good close process should have proper controls at various stages of the process. Account reconciliation is an important part of the close process and involves comparing accounting records with supporting records, bank statements and subsidiary systems.
The preparation and approval of journal entries should also be subject to defined procedures. Significant or unusual journal entries may require additional review and approval before they are reflected in the financial statements.
Other controls that are useful include:
Close Checklists
A close checklist can include specific activities, deadlines and responsible personnel. This provides finance teams with visibility into tasks that are not yet done and helps minimize the risk of important tasks being missed.
The controls and related activities should be reviewed and approved by appropriate personnel.
Appropriate personnel should review financial statements and make significant adjustments prior to the finalization of the report. Clear approval thresholds can help to ensure that changes are not made without authority and provide greater accountability.
Cut-Off Controls
Transactions need to be booked in the relevant accounting period. The review of the cut-off can help to determine if revenue, expenses, accruals and other transactions have been recorded at the wrong time.
Exception Monitoring
It’s not only about reviewing all the transactions manually, but it also entails setting up processes to look for unusual balances, major fluctuations, or unusual entries. Any exceptions can then be explored prior to the closing.
Assessing the Applicability of Internal Financial Controls
All organizations are not the same. The nature and extent of internal financial controls required may depend on factors such as the size and structure of the organization, regulatory requirements, transaction complexity and financial reporting risks.
When assessing their existing controls, businesses should then consider if these are suitable for their operations. This evaluation can help to uncover unclear accountability, duplicated controls, and unaddressed risks that are critical to the business.
Technology can help support the process with automated reconciliations, workflow-based approving, tracking deadlines and exception alerts. Automation should not replace well-established responsibilities and review processes, though.
Establishing a Reliable Financial Close Process
But working faster is not enough to get a timely financial close. It needs to be a step-by-step process that has clear ownership, adequate control and proper documentation.
Businesses have to revisit their closing process to make sure that the controls are appropriate for their needs. In case gaps are identified, the management could revamp the workflow, define responsibilities, and improve the review process.
Organizations can achieve more reliable financial reporting by emphasizing timely and accurate information. A close process that is well controlled A well-controlled close process can support management by providing timely and reliable financial information for decision-making and reducing the risk of reporting errors.
FAQs
Q1. What are financial close controls?
Financial close controls verify transactions, balances and adjustments to support accurate and timely reporting.
Q2. Why are account reconciliations important?
Account reconciliations help detect incorrect balances, missing entries and differences in supporting records.
Q3. What is a financial close checklist?
A financial close checklist records closing activities, responsible employees, deadlines and approval requirements.
Q4. What are cut-off controls?
Cut-off controls ensure that revenue, expenses and other transactions are recorded in the correct accounting period.
Q5. Can financial closing be automated?
Yes, technology can automate reconciliations, deadline tracking, approvals and unusual transaction alerts.
Also Read: How Internal Financial Controls Detect Financial Irregularities Early